Blog
How a Maryland Roof Insurance Claim Works
Diakite Roofing & Restoration handles storm and hail damage roof claims in Columbia, MD and across Howard County. Covered against excluded, what an adjuster expects to see, and the parts of a claim nobody can promise you.
We document storm damage slope by slope and write the scope in Xactimate, the software your carrier already prices from. Our owner does the inspections himself.
Keep reading: whether vinyl siding can be painted, and what to expect when a roofer gets on your roof.
What a policy usually pays for
Policies generally cover sudden storm damage: wind that lifts or creases shingles, hail that fractures the mat, a limb that comes through. What they exclude is a roof that wore out. Age, deferred maintenance and a system at the end of its service life are written into most policies as exclusions.
Most claims come down to that line between an event and ordinary wear.
How hail damage gets documented
Hail rarely looks like anything from the ground. A hit bruises the shingle, fracturing the fiberglass mat under the surface and knocking granules loose in a soft circle. Our guide on how to spot hail damage on your roof walks through the signs you can catch from the ground.
The mat is the shingle's structure, and the granules protect the asphalt from the sun.
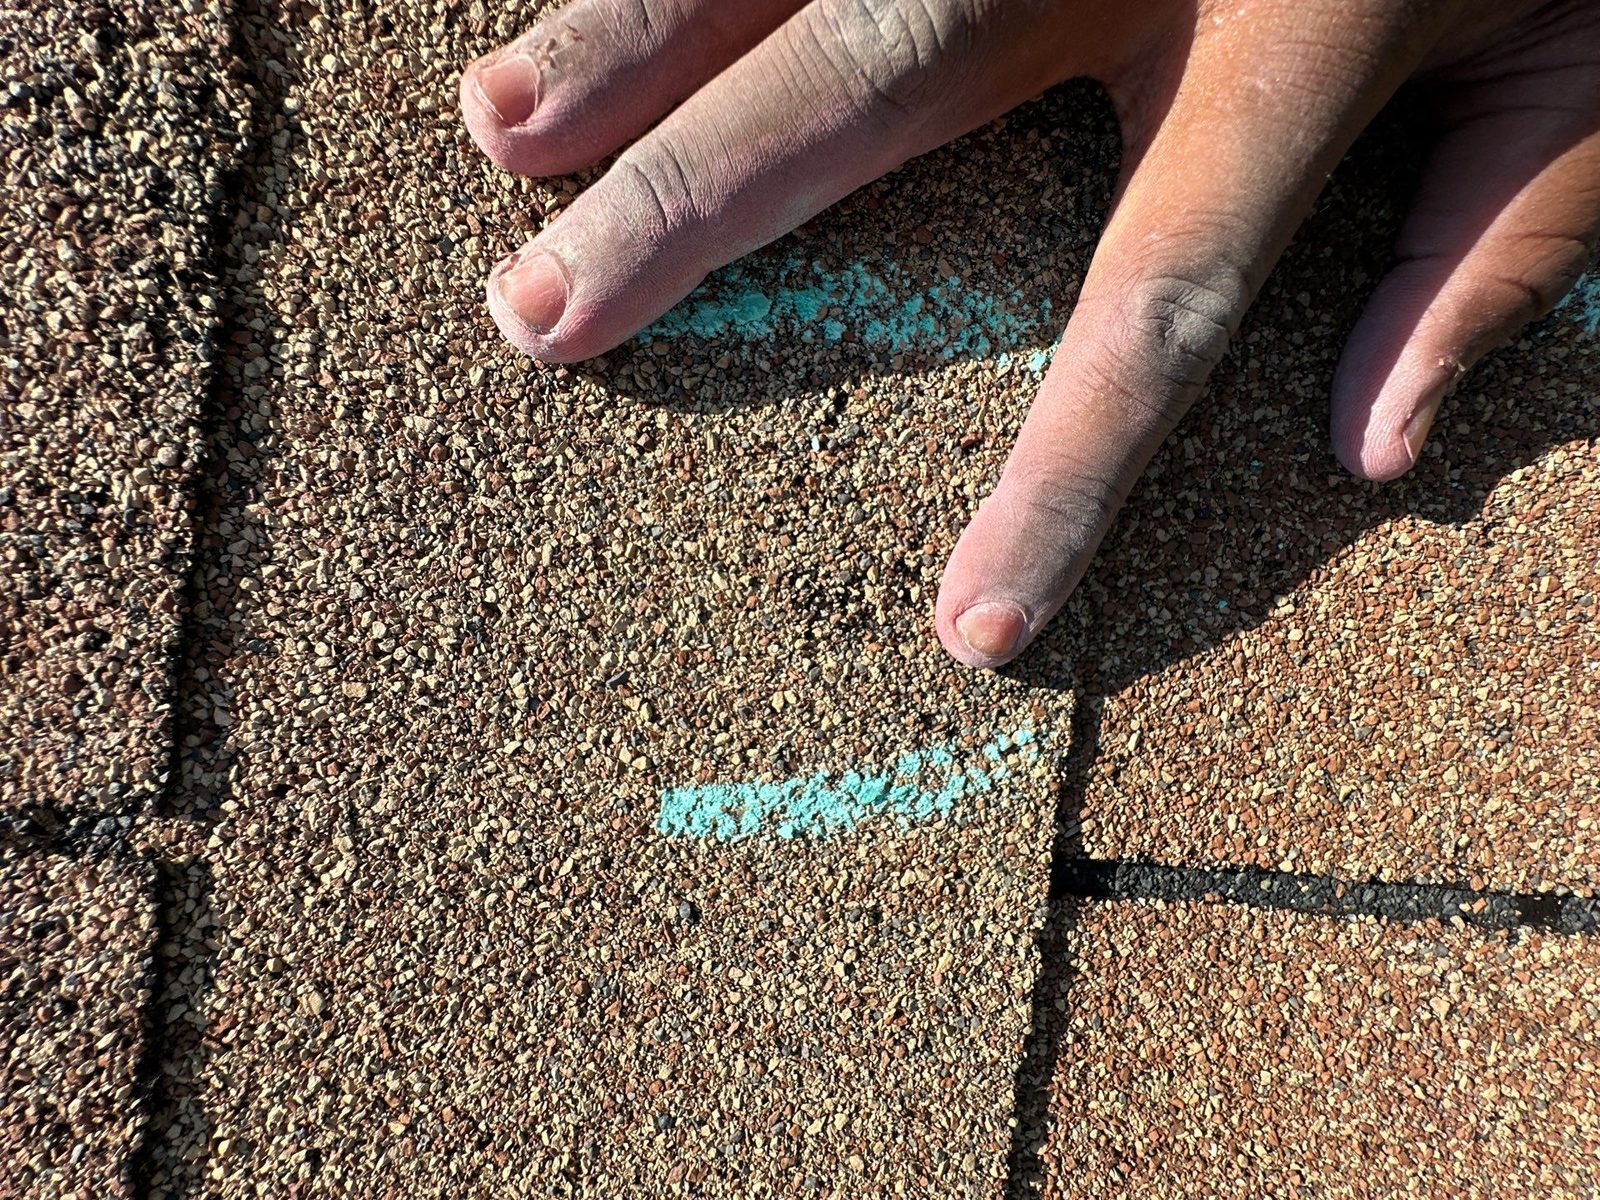
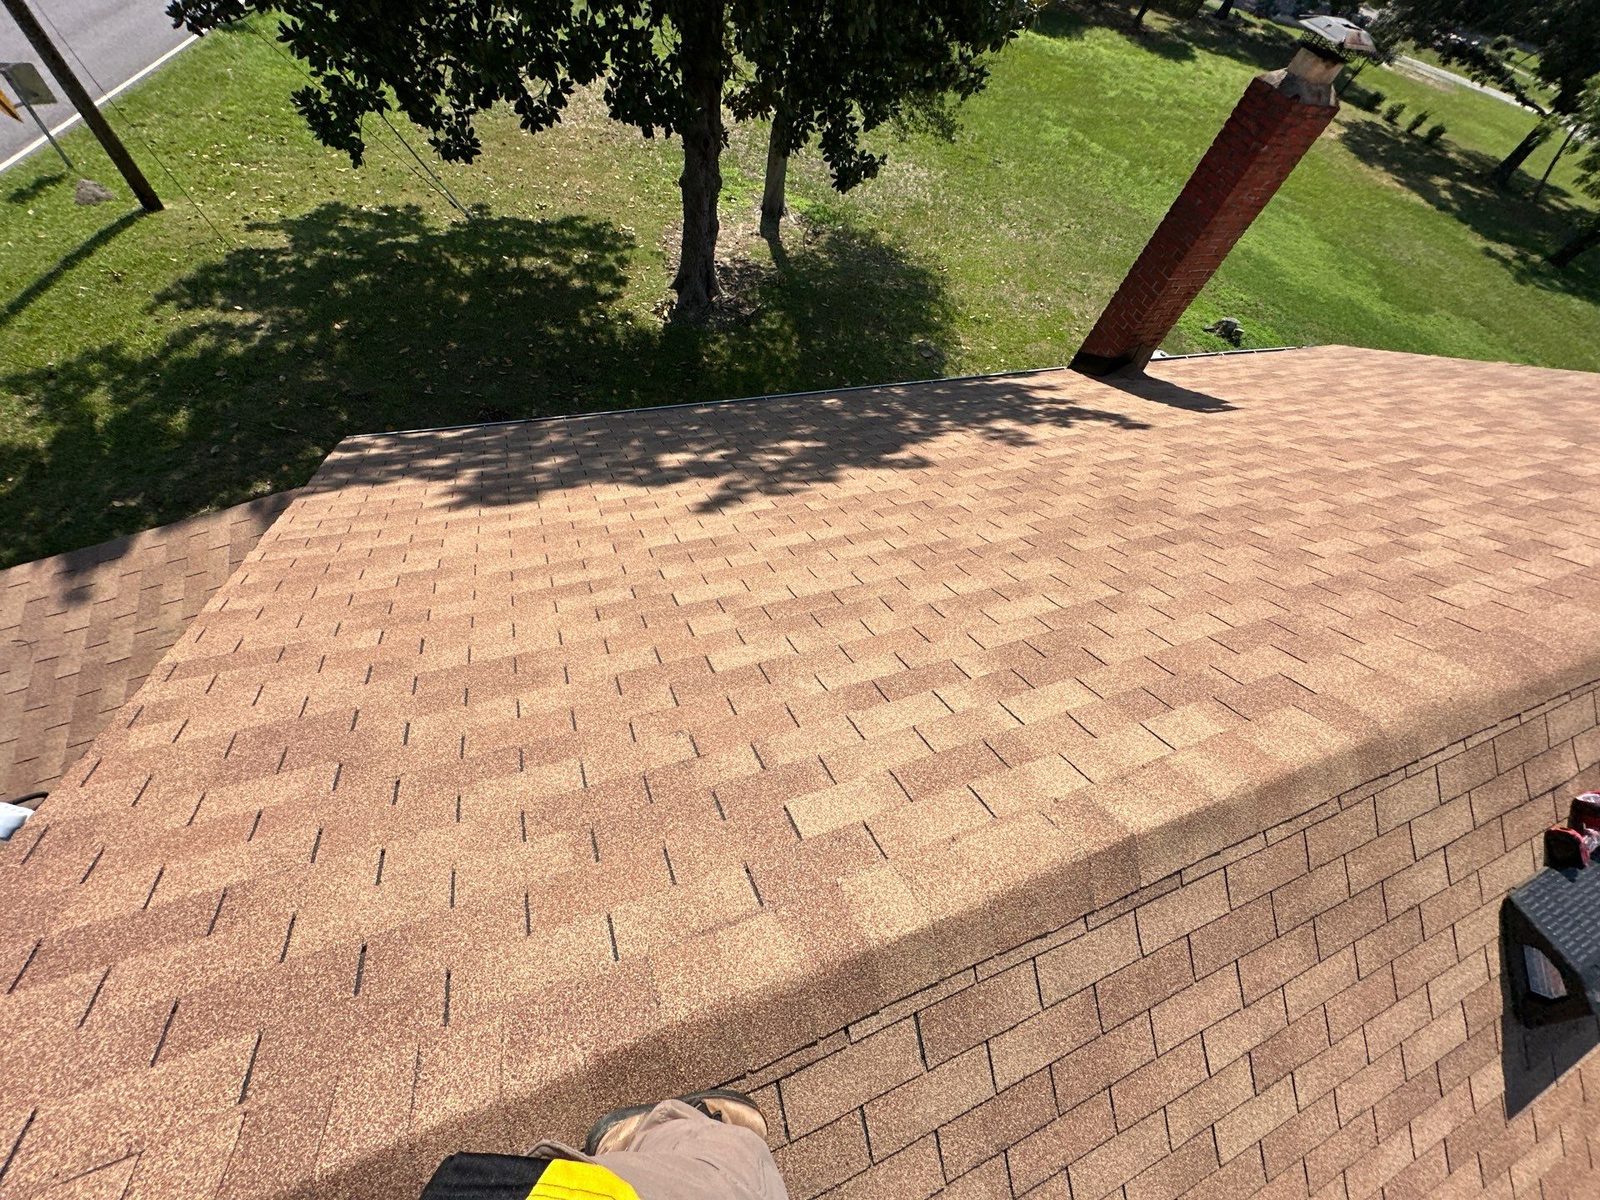
On a storm inspection the slopes get chalked into test squares, and the strikes inside each square get counted and photographed. That is the same test-square method adjusters use on a hail claim.
Hail bruising can stay hard to see for a year or two while the filing deadline keeps running. Policies set their own filing deadlines and they are usually shorter than people expect, so the date of the storm matters more than the date you noticed.
Why the scope is written in Xactimate
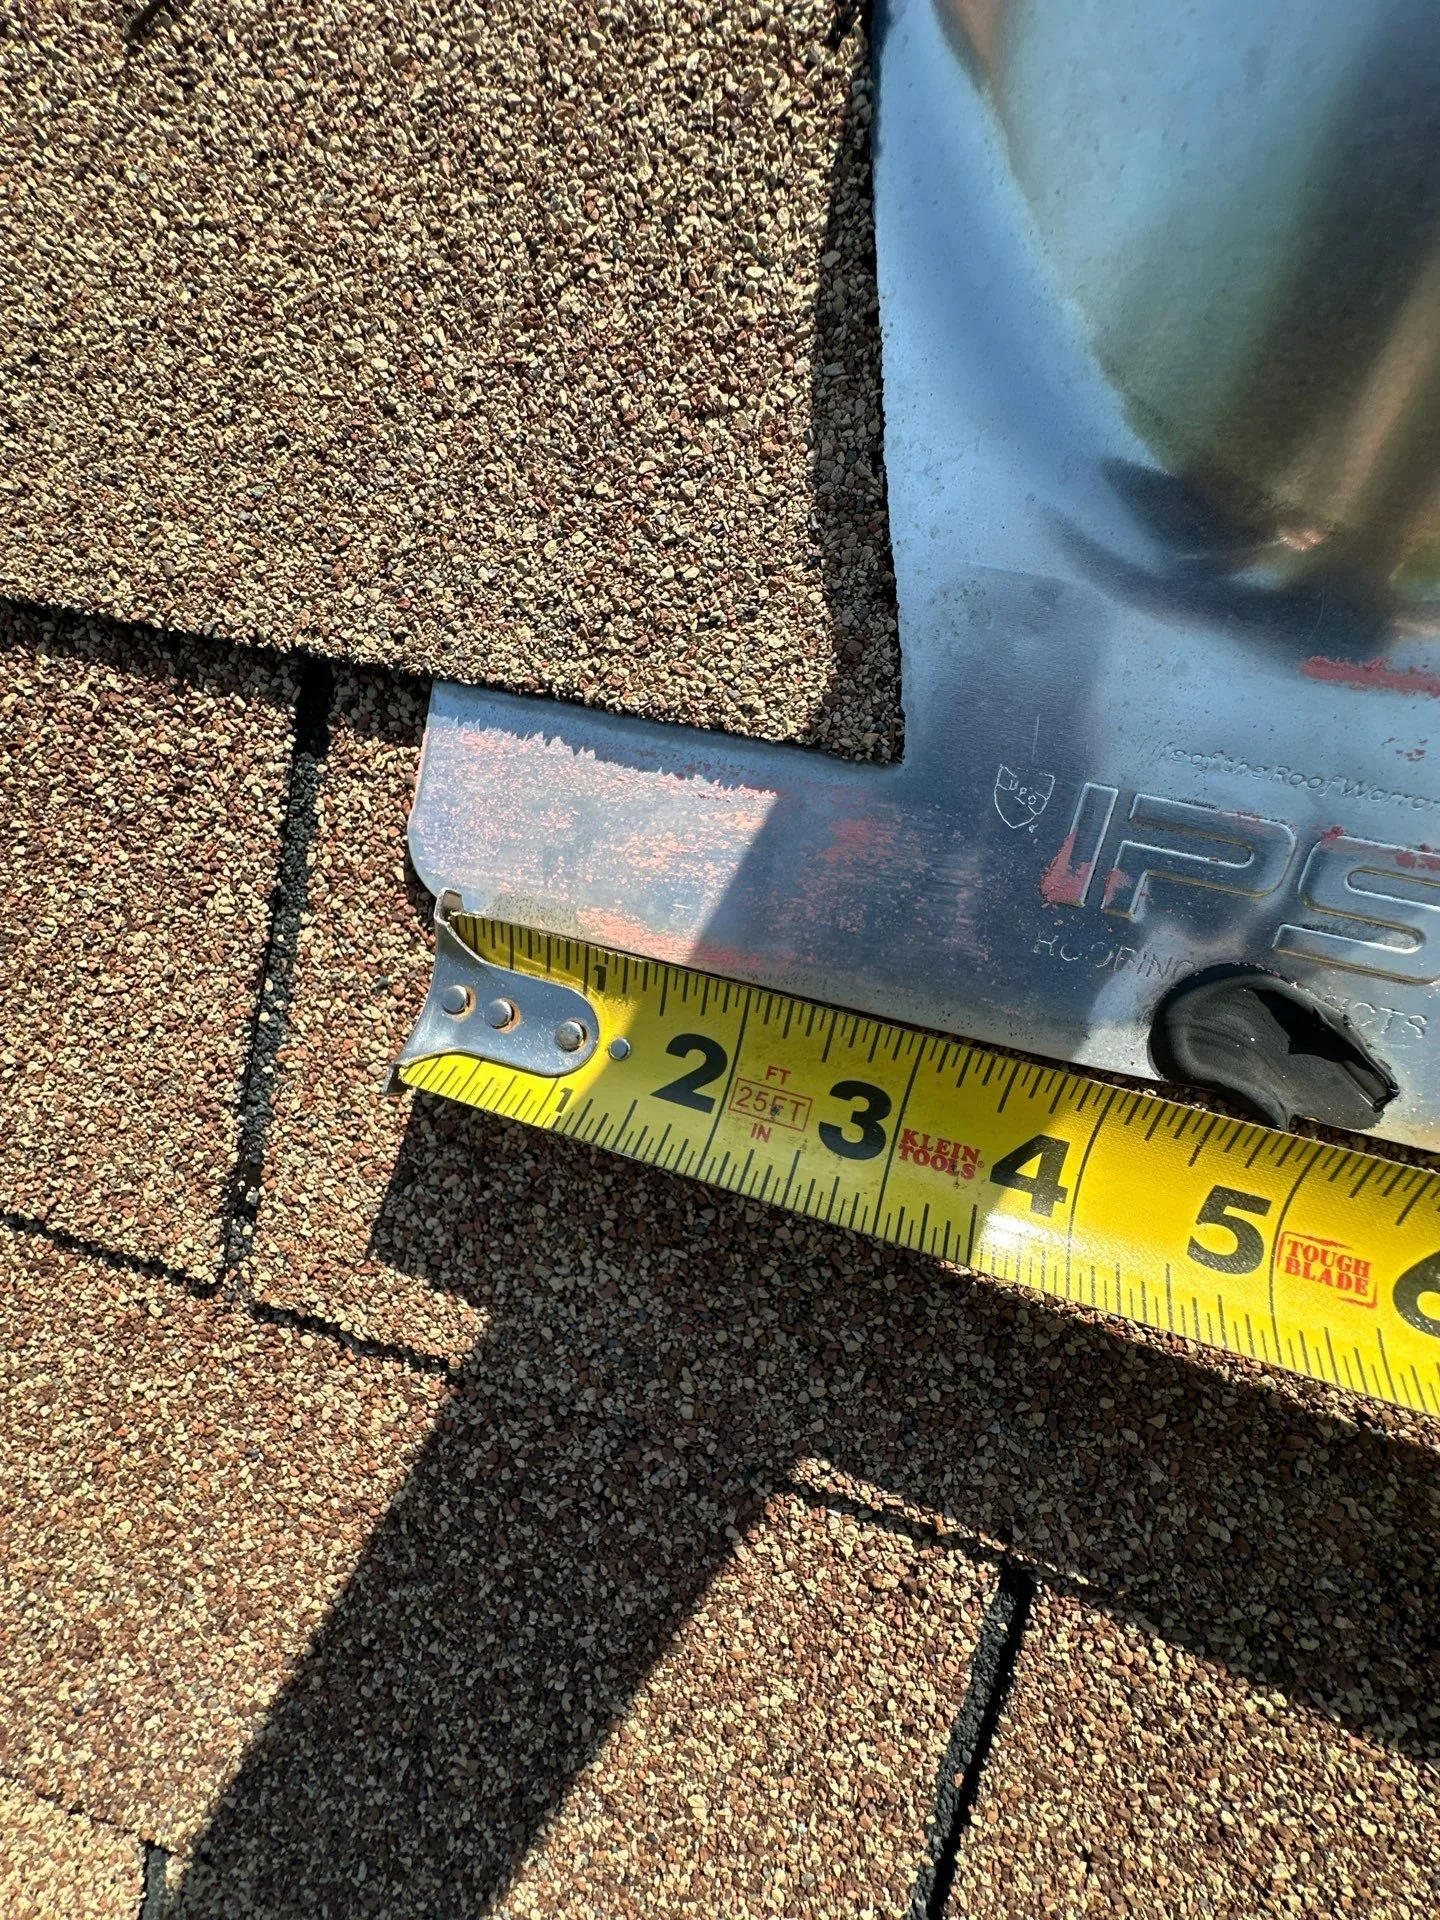
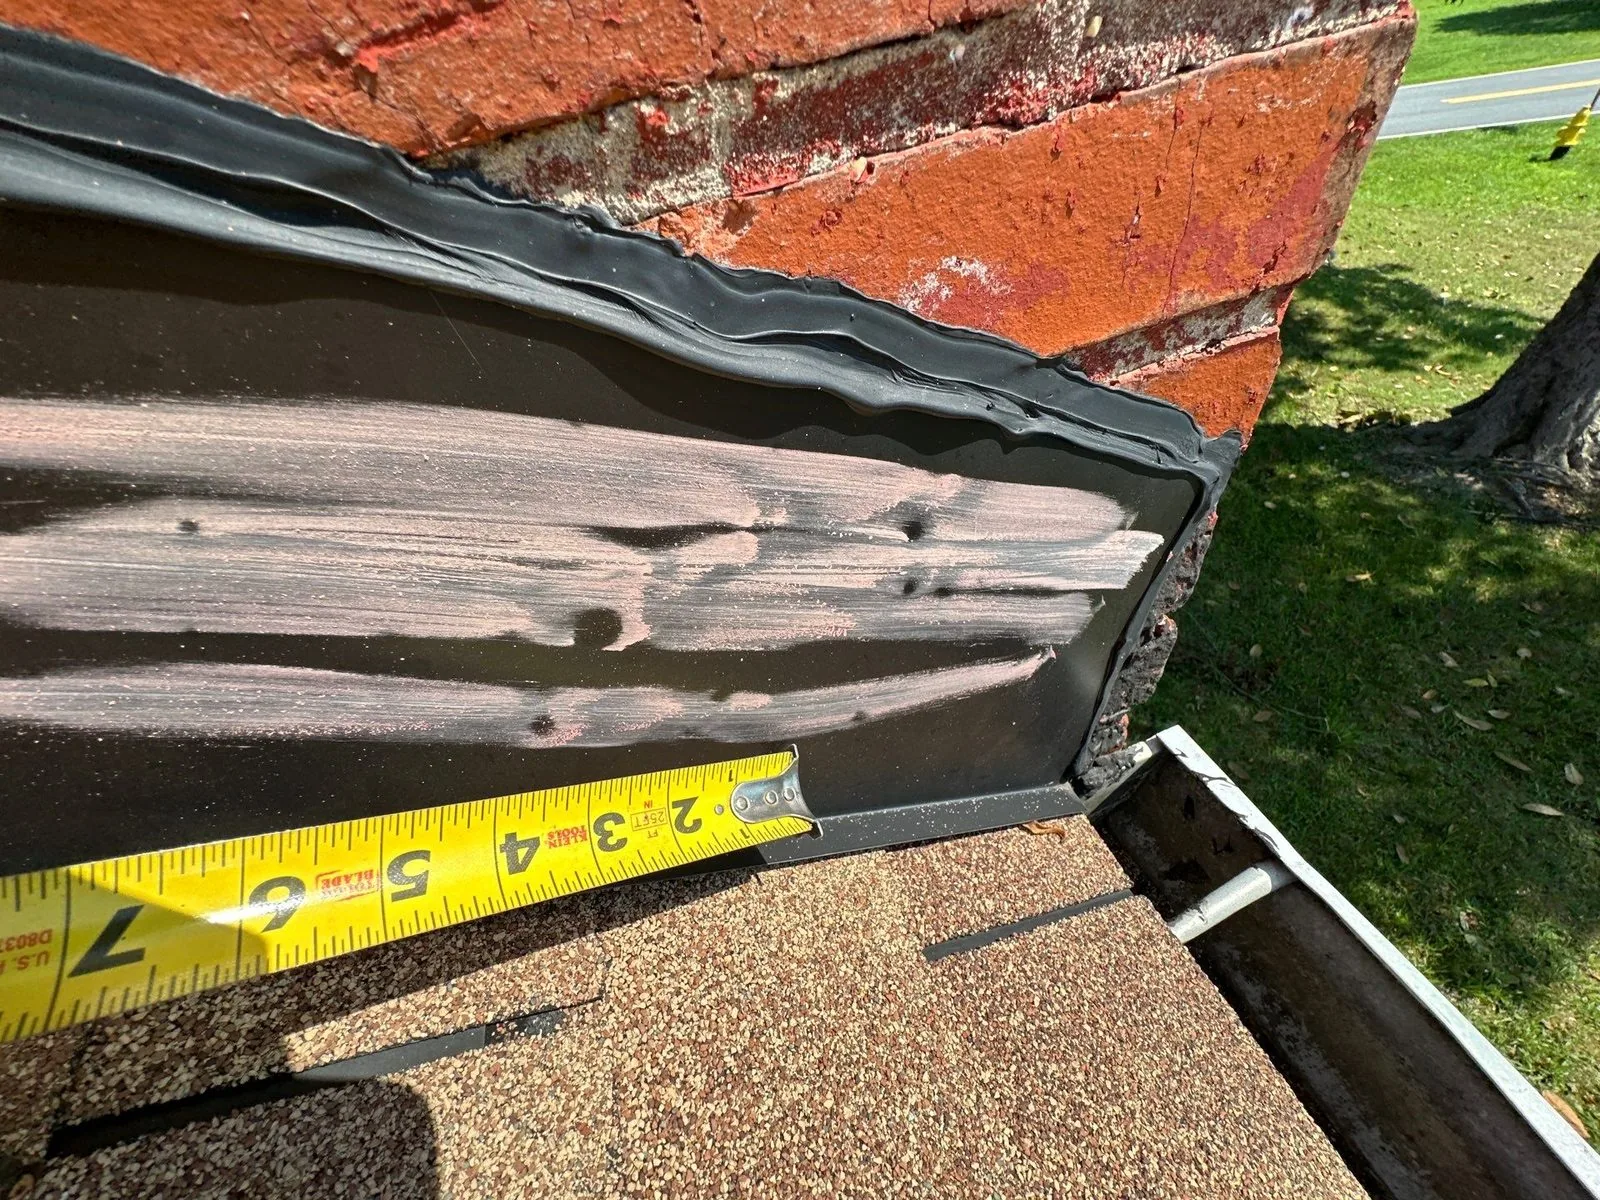
Xactimate is the estimating software the carriers use, carrying the same regional pricing they price from. Writing the scope in it removes an entire argument from the process. When an adjuster's estimate is missing drip edge, or pays for a ridge vent it never accounted for, the disagreement gets settled on a line rather than over the phone.
Supplements work the same way. Rotted decking found under an old skylight curb after tear-off goes into the file as a line item with a photograph attached, not as a phone call asking for more money.
What nobody can promise you
The carrier decides coverage and we do not. Deductibles apply.
Some policies pay depreciated value up front and release the rest once the work is finished, which changes what lands in your account and when. A roof already at the end of its life sometimes gets denied, and sometimes that denial is correct.
If the roof is open the order changes. It gets tarped and the condition documented while it is fresh, then the claim gets worked from a house that is no longer taking on water. An insurer looks harder at a file where the damage was left to spread.
The storms that drive claims here
The derecho of June 29, 2012 crossed the Baltimore-Washington corridor with gusts reported as high as 87 mph, knocked out power to roughly 1.6 million Maryland customers, and left uprooted trees on residential roofs across the region. Hurricane Isabel in September 2003 cut power to about 1.24 million customers across Maryland and Washington and left around 945 million dollars in damage between them, with storm surge flooding reported in Baltimore and Annapolis.
Those are exactly the kind of sudden, dateable events a homeowners policy is built to respond to. A tree through the decking on June 29 reads as an event.
Great job on my roof in Glen Burnie. Handled all the insurance claim. Very good crew. No complaints the roof look great, great clean up as well. I highly recommend.David G · Google review
A slope that shed its granules slowly over years reads as wear. Most contested roof claims fall between those two, which is why the storm date, the chalked test squares and the slope-by-slope photographs end up deciding more than any phone argument does.
After a widely reported storm the adjusters are working a lot of claims at once. A claim that arrives documented, with the damage photographed in place and the scope in the software the carrier already uses, moves through differently than one that arrives as a phone call.
The first days after a storm
Walk the yard, not the roof. Shingle pieces on the lawn, granules banked at the downspout splash blocks, a limb resting where it should not be. Photograph what you find where it lies, note the date of the storm, and leave the slopes to someone who is paid to walk them.
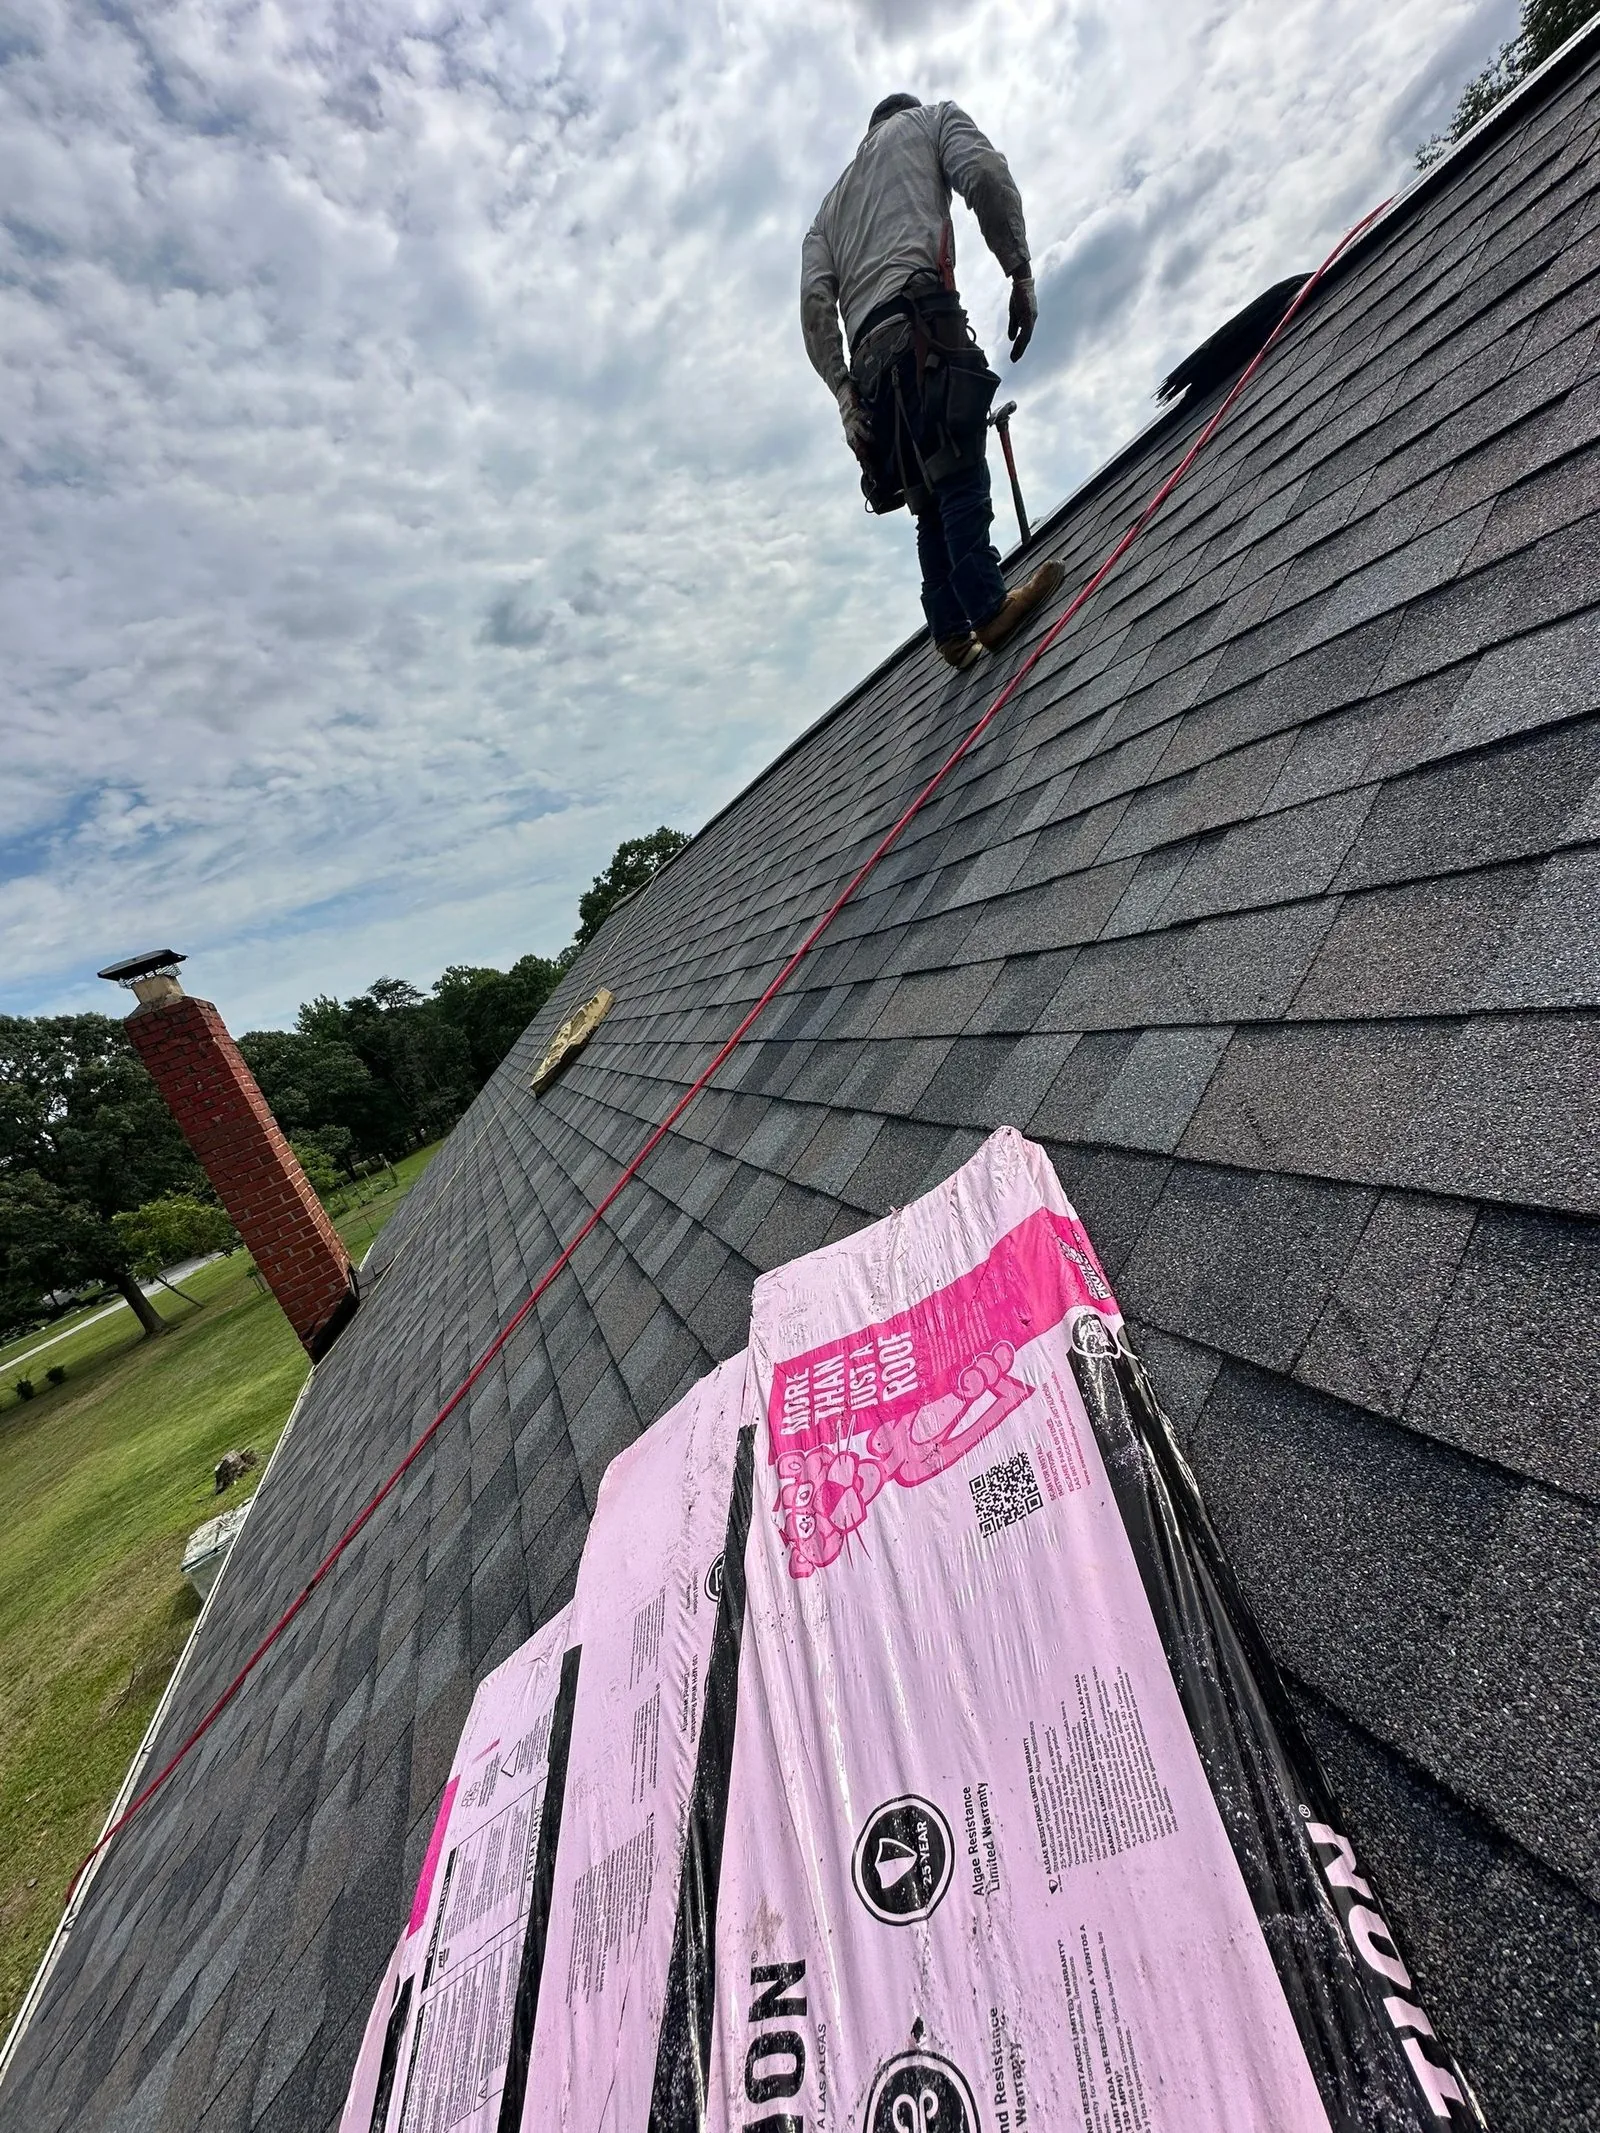
If water is coming in, the tarp comes before the paperwork every time. A dried-in roof stops the damage where it stands, and the condition gets documented while it is fresh. What you should not do is wait for a convenient week: the storm date anchors the claim, and a file that shows the damage was contained quickly reads better than one where it was left to spread.
The inspection that starts all of this is free, and if the slopes come back clean you will be told exactly that.
If you and your carrier disagree
Start with the file, not the phone. A denied or short-paid claim usually turns on a specific line, and a supplement with a photograph attached answers a specific line. That is the normal back-and-forth of a claim, not a fight.
If it genuinely stalls, the Maryland Insurance Administration is the state agency that regulates insurers doing business in Maryland, and its stated role is to protect consumers by making sure insurers operate in accordance with state insurance law.
It accepts consumer complaints about homeowners policies. Your policy's own deadlines and terms still govern, and your declarations page is where they live.
In a dispute we bring the photographs taken on the roof and the scope written in Xactimate, and we do not promise an outcome.
Usually covered, usually excluded
| Usually covered | Usually excluded |
|---|---|
| Wind that lifts, creases or tears shingles | Shingles worn out by age |
| Hail that fractures the mat under the surface | Granule loss from ordinary weathering |
| Impact damage from a fallen limb | Damage traced to deferred maintenance |
| Interior water damage from a sudden opening | Slow leaks that were left to run |
The general shape of a homeowners policy, not a reading of yours. Your declarations page and its exclusions are what govern, and carriers differ. When a claim turns on one of these lines, the photographs taken on the roof are what settle it.
What to do with any of this
The free roof inspection gets you a set of photographs of your own roof, and it is where a storm and hail damage restoration conversation starts if it turns out you need one. Read the storm & hail damage restoration page for how that job actually runs.
We work Mon-Sat 8:00 AM - 5:00 PM across Howard, Anne Arundel, Montgomery, Prince George's, Carroll, Frederick & Baltimore Counties.
Frequently asked questions
Does homeowners insurance cover roof replacement in Central Maryland?
Usually, when the damage is sudden and storm related: wind, hail or impact. A roof that simply wore out is excluded on most policies. The carrier decides, and the deciding factor is almost always whether the damage reads as an event or as age.
How do I tell if my roof has hail damage in Howard County?
Mostly you cannot, not from the ground. A hit bruises the mat under the surface and knocks granules loose in a soft circle, which is visible on the slope and invisible from the driveway. Test squares chalked on each slope and photographed is how it gets established.
What is Xactimate, and why does it matter on a Maryland roof claim?
It is the estimating platform the carriers use, with the same regional pricing. A scope written in it lines up with what your adjuster is already reading, so a missing item gets settled as a line rather than as an argument.
How long do I have to file a roof damage claim?
Your policy sets that deadline, not us, and it is usually shorter than people expect. Check the declarations page. Hail bruising can stay invisible for a year or more, so the storm date matters more than when you spotted it.
Will filing a roof claim raise my premium?
That is a carrier decision, and nobody outside your insurer can answer it honestly for your policy. Ask your agent before you file.
Who do I contact if my Maryland roof claim is handled unfairly?
The Maryland Insurance Administration, the state agency that regulates insurers operating in Maryland. It accepts consumer complaints about homeowners policies. Before you get there, ask for the denial in writing and match it against the photographs in your file, because most disputes are settled by the file.
Think a storm damaged your roof?
Free no-obligation inspections · Central Maryland · Mon-Sat 8:00 AM - 5:00 PM